How a roof claim works
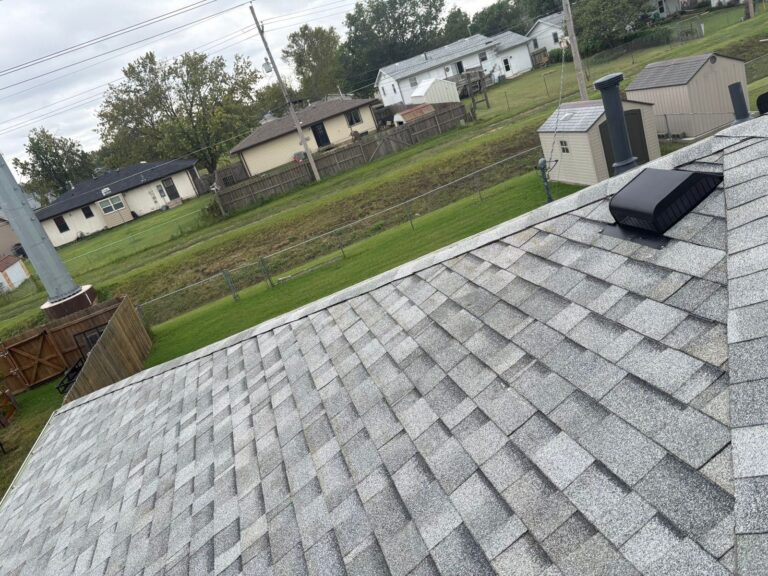
- Documented inspection. Photos of each damaged element, tied to the storm date and local weather data.
- You file the claim with your carrier. They assign an adjuster and a claim number.
- Adjuster inspection. We meet them on the roof, walk the damage together and hand over our scope, so the estimate is built from the same facts.
- Scope and settlement. The carrier issues an estimate. Missed items — and they are common — get supplemented with documentation.
- Work and final payment. We complete the repair or replacement; the carrier releases the remaining depreciation once the work is invoiced.
ACV vs. RCV, in plain terms
| ACV — actual cash value | RCV — replacement cost value | |
|---|---|---|
| Pays | What the roof was worth, with age depreciated out | What it costs to replace at today’s prices |
| You receive | One payment, minus deductible and depreciation | An initial payment, then the withheld depreciation after the work is done |
| Means for you | A larger out-of-pocket share on an older roof | Lower out of pocket, but the work has to be completed and invoiced |
Check which one your policy carries before a storm, not after. On an RCV policy, the depreciation is recoverable — which is exactly why the job needs to be documented and invoiced properly.
What we can and cannot do
We are roofers, not public adjusters or attorneys, and we do not negotiate your claim for you or waive deductibles — waiving a deductible is illegal in many states and a red flag whoever offers it. What we do is document the damage thoroughly, show up for the adjuster meeting, explain the roofing scope in terms the carrier prices from, and supply evidence for anything that was missed.
Frequently asked questions
Will filing a claim raise my premium?
Weather claims are treated differently from liability claims, and a single storm claim in a region-wide hail event usually affects rates less than people expect — but carriers set their own rules. Ask your agent about your specific policy before filing.
What if my claim is denied?
Denials are often about documentation rather than the damage itself. You can request a second inspection or re-inspection with better evidence, and policies generally include an appraisal process for disputes over amount. We will provide the roofing documentation for either.
Should the roofer be there when the adjuster comes?
Yes. It is the single most useful hour in the process. Two sets of eyes on the same roof at the same time prevents most disagreements about scope later.
How long does approval take?
Days to several weeks, depending on the carrier and how many claims a storm generated in your area. Regional hail events slow everything down, which is another argument for filing early.
Insurance terms vary by policy and state, and this page is general information, not insurance advice — your carrier and agent are the authority on your coverage.